Accounting software integrations offered by automated business valuation platforms
Integrations pull data pipes, not judgments—here's what that actually means.
Automated business valuation platforms sell speed and accuracy, and both promises rest on one unglamorous fact: where the numbers actually come from. This piece looks at what accounting software integrations inside these platforms do, what they quietly skip, and why "connected to QuickBooks" and "produces a defensible valuation" are not the same claim, no matter what the product page implies. An integration is a data pipe, not a judgment engine. Most of the platforms covered here are better at the pipe than they'll admit, and the ones worth paying for are the ones that say so out loud.
Why QuickBooks and Xero dominate every platform's integration roadmap
QuickBooks holds roughly 62% market share among accounting platforms. That number alone explains why every valuation platform built for this segment treats QuickBooks as table stakes. A tool that doesn't connect to it isn't serious about the SMB market, full stop.
Xero tells a related but distinct story. Founded in 2006, it now counts 4.4 million subscribers across more than 180 countries and has built an app ecosystem north of 1,000 third-party connections, compared to roughly 750 for QuickBooks. Xero didn't win on raw market share. It won on being easier to plug things into, which is a different kind of advantage and arguably a more durable one.
Enterprise companies run SAP or Oracle, a separate universe with its own vendors and its own valuation tooling, and nothing here concerns that world. The platforms covered in this piece are built almost exclusively around the QuickBooks and Xero duopoly, and that has real consequences for anyone running something else. Sage, FreshBooks, MYOB, Zoho Books: none of these integrations could be confirmed inside the named valuation platforms during this research. Take that as unconfirmed, not as proof of exclusion. Maybe some of these connections exist quietly, maybe they don't. Either way, an owner running one of those systems needs to call the vendor and ask directly, because guessing here is expensive, and "probably compatible" is not an answer a buyer's diligence team will accept later.
What each major platform actually connects to and what that connection does
BizEquity confirmed QuickBooks Online and Xero integrations, with the QuickBooks connection formally announced October 23, 2024 through PR Newswire. The pitch is a one-step setup that feeds BizEquity's patented seven-step valuation process straight from a QuickBooks account, cutting manual entry out of that workflow entirely. Over 5,000 financial advisors, accountants, and consultants use the platform, which claims to have valued more than 33.3 million private businesses globally. It's built for non-financial users who want a fast, dependable number without wading into methodology, and the integration is the thing that makes that possible.
Capitaliz also connects to QuickBooks and Xero, pulling financial and operational balance sheets through to profit and loss reports, then sorting that data into its own Business Insights Report categories. What sets it apart isn't the pull itself but what happens after: the Dynamic Revaluation™ engine uses that live feed to update valuations instantly as relevant business tasks get completed, benchmarking against a dataset of over 800 businesses across 21 steps. Underneath sits the VPI™ algorithm, built on close to a million data points gathered over 12 years. The integration here isn't really the feature. It's the fuel line for a much bigger engine.
PlanGuru takes a broader integration stance: QuickBooks (both desktop and Online), Xero, Excel import, and an API for custom connections. It pulls up to five years of historical actuals, deeper than most competitors confirm, and its general ledger utilities stretch compatibility to accounting systems beyond the primary two. PlanGuru is really a forecasting and planning tool with a valuation feature bolted on, supporting more than 20 standard forecasting methods, and it starts at $99 a month.
Equitest could not be confirmed to have named API connectors for QuickBooks or Xero in the sources available, so treat that as an open question, not a settled one. The platform leans on AI-driven data input and serves financial professionals across 152 countries in 22 languages, covering DCF, DLOM, 409A work, and comparable company analysis with audit-ready output. Pricing starts at $99 as a one-time fee for certain tiers. Anyone considering it should confirm integration specifics with the vendor directly, rather than assuming parity with BizEquity or Capitaliz.
LivePlan lists Xero as a native integration alongside QuickBooks, feeding a dashboard built for financial plans, budgets, and real-time plan-versus-actual comparisons. LivePlan isn't really a valuation platform, and it's worth being blunt about that. It's a planning and budgeting tool with valuation-adjacent output, and the accounting connection exists to support monitoring, not to generate a standalone business value.
ValuAdder doesn't document a live QuickBooks or Xero API connection in the sources reviewed here. Its workflow instead relies on the appraiser importing or manually entering structured data, and that's not a knock on the tool. ValuAdder has been trusted by over 22,920 valuation professionals since 2004 and picked up a CPA Practice Advisor Readers' Choice Award in 2021. It covers all three standard valuation approaches (asset, income, market), with built-in cost of capital data, DLOM calculations, and a Multiples Maker™ tool for normalizing comparable transactions. This is a professional-grade, USPAP-compliant tool built for credentialed appraisers, where judgment and auditability matter more than an automatic data pull.
Kroll's Valuation Platform doesn't show confirmed SMB accounting integrations either, and that's because it isn't built for this audience. It targets enterprise and private equity users, managing valuation data and automating calculations across multiple asset classes with customizable workflows. It's useful for seeing the ceiling of what this category can do, but it has little to say to a business owner running QuickBooks out of a home office.
What the integration actually pulls, and what it leaves out
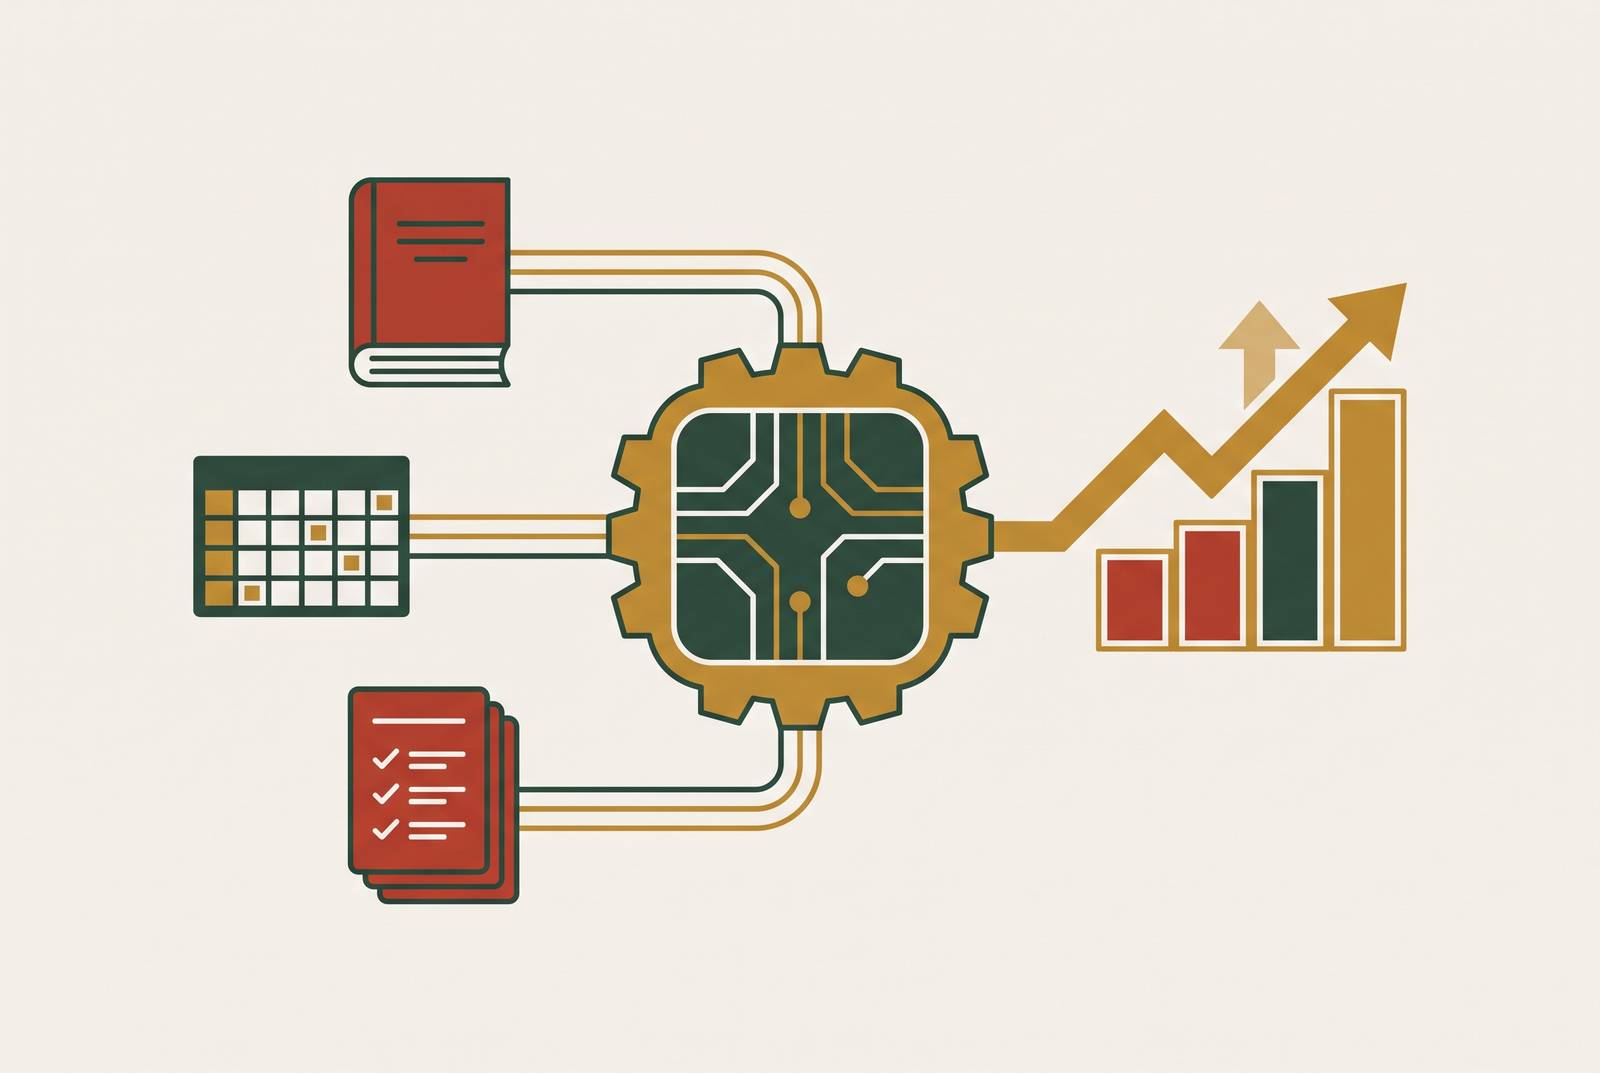
Strip away the branding, and a QuickBooks or Xero connection typically hands a valuation platform the same core ingredients: income statement line items (revenue, cost of goods sold, operating expenses), balance sheet categories (assets and liabilities), and in some cases up to five years of historical results. Platforms layer pre-loaded industry benchmark data on top of that, so once an owner picks an industry classification, comparable figures populate without anyone retyping a single number.
From there, standard methodologies (DCF, market multiples, asset-based approaches) apply automatically, producing a preliminary valuation range in a matter of minutes. Compare that to the 8 to 12 hours a credentialed appraiser might spend manually reconciling the same source documents by hand. The time saved isn't a marginal improvement. It's structural.
But here's the catch, and it's the hinge the rest of this piece turns on. The integration reads the numbers exactly as they were recorded. It never asks whether those numbers are correct, adjusted, or representative of how the business actually performs. That sounds like a small distinction. It isn't, and the next section spells out exactly why.
Where accounting integrations fall short and why that matters for valuation accuracy
Here's the failure mode in concrete terms, because "the data isn't perfect" undersells it. An automated pull can't tell the difference between an operating expense and a one-time write-off buried in the same account code, so both get treated as recurring cost. Related-party transactions flow through at book value with no flag attached, no matter how far off market rate they actually sit. Owner compensation shows up exactly as recorded in payroll: if the owner pays themselves well below what a market-rate general manager would cost, the integration has no way to know that, and it carries the $40,000 straight into EBITDA untouched.
Every one of these gaps feeds directly into EBITDA, and EBITDA is the number every multiple-based valuation method sits on top of. Miscalculate that figure by even a modest percentage, and the resulting valuation range can shift by tens of thousands of dollars, sometimes more, depending on the multiple applied. A significant compensation gap run through a standard valuation multiple isn't a rounding error. It can produce a substantial swing in what a business is supposedly worth, generated entirely by a field the integration was never built to question.
Then there's the PDF problem, and it's a real one. In estate planning, litigation, or tax-return-based engagements, financials often arrive as scanned documents rather than live data pulled from a connected system. The integration has nothing to offer here. The bottleneck reverts straight to manual re-entry, the exact problem these tools were built to solve in the first place.
Unsupported accounting systems compound the issue further. An owner running a regional package, an industry-specific system, or something legacy and unglamorous simply can't connect, and the whole promise of "instant, error-free data" evaporates for that segment. Historical depth is its own quiet limitation, too: many integrations only pull current or recent-period data, and for a business whose valuation story depends on a multi-year trend line, a shallow pull tells half the story at best.
A 2025 guide from V7 Labs framed this as a "calculation engine versus data pipeline" problem, and that framing holds up. Valuation software is genuinely good at applying methodology once the data feeding it is clean and properly structured, so it solves speed. It does not solve interpretation, and that gap matters more than the market size numbers suggest, given that this segment was valued at USD 1.2 billion in 2023 and is projected to reach USD 3.5 billion by 2033. Despite that growth, credentialed appraisers still spend real hours manually reconciling data before any analysis starts. The bottleneck was never the math. It's the quality of what feeds the math, and no amount of processing speed fixes a dirty input.
How platforms and practices are compensating for what integrations cannot do
The stronger platforms in this category don't pretend the gap doesn't exist. They build fallback tiers instead: drag-and-drop Excel and CSV import, pre-built templates, and manual override fields for figures the live connection can't, or shouldn't, carry through untouched. That override is what lets an owner or advisor normalize owner compensation or strip out a one-time expense, even when the automated feed has no built-in way to flag it. A platform without that override isn't more automated. It's just less honest about where automation stops.
A composable stack approach has taken hold among leading valuation practices as of 2025, and it's worth unpacking because it reframes the whole integration question. Instead of treating data extraction and calculation as one seamless step, practices separate them on purpose. Tools using OCR and large language models read scanned documents, normalize inconsistent account structures, and output a clean dataset. Only then does an appraiser review that output before it moves downstream into the valuation engine. The human checkpoint sits in the middle of the process, not tacked onto the end of it.
Capitaliz's Dynamic Revaluation™ shows this same logic in a slightly different form. The live accounting feed is the raw input, but the interpretive work happens in the 800-plus business dataset and the 21-step process layered on top. The integration alone was never the valuation. It's the ingredient, not the dish. PlanGuru's general ledger utilities point at a more practical fix for a narrower problem: owners who aren't on QuickBooks or Xero at all still need a path in, and broader system compatibility is one honest way to build it.
A platform that pulls clean data and lets someone adjust it afterward beats a platform that pulls automatically but locks the output, every time. Automation without an override isn't a shortcut. It's just a faster way to be wrong, and a faster wrong number does more damage than a slower right one, because it gets acted on before anyone thinks to question it.
How AI-assisted valuation from an advisory platform fits into this picture
Every gap covered so far, normalization, owner-compensation adjustment, strategic context, points toward the same conclusion: software handles retrieval well and interpretation poorly. That's not a knock on the engineering behind it. It's a structural limit on what a data pipeline can reasonably be expected to do by itself.
A different category of tool has emerged to sit on top of that limit instead of ignoring it. Some advisory platforms, such as Succession AI, a Toronto-based M&A platform for founder-led businesses, combine algorithmic analysis with a human review layer, and that human layer is precisely what addresses the normalization problem an accounting integration can't touch on its own. Platforms operating in this space pair automated valuation with human review, on the premise that a clean data pull and a defensible valuation are related things, not identical ones.
This matters especially for Canadian business owners in the SMB segment. That group is among the core user bases for QuickBooks and Xero, and it's also, not coincidentally, the group most likely to mis-normalize its own financials when left alone with a self-serve tool. An owner who doesn't adjust their own salary line to market rate is running headfirst into the exact limitation this piece has been tracing from the start.
None of this replaces the accounting integration. It operates one stage later, once the raw numbers are already sitting there waiting to be interpreted. Once an owner has a working sense of their valuation range, the advisory layer takes over for buyer matching, process management, and negotiation, none of which software alone has much capacity to do. For an owner not yet approaching a transaction, a self-serve tool with a solid integration is a reasonable way to track value over time. For an owner approaching an actual transaction, pairing that data with professional advisory tends to produce a more defensible outcome than either piece running alone.
What to actually check when comparing these platforms on integration quality
Start with the basic compatibility question: does the platform connect to the accounting system through a live API, or does it fall back to CSV import, or is it manual entry only? That answer alone rules half the field in or out for most owners before anything else gets considered.
From there, check how many years of historical data actually get pulled, and whether that depth matches the story the business needs to tell. A five-year pull, which PlanGuru supports, tells a very different story than a single current-period snapshot does. Ask, too, whether the platform allows manual override and normalization, specifically for owner compensation, related-party transactions, and anything non-recurring. A tool that locks these figures in as recorded is asking the owner to accept book-value accuracy as market-value truth, and those are rarely the same number, sometimes not even close.
Worth understanding, too, what the platform actually does with the data once it lands. Does it apply one methodology or several (DCF, market multiples, asset-based), and are the underlying assumptions visible and adjustable, or buried behind a single output figure? Security deserves a real look here as well. Data security ranks as a leading concern among professional services users of AI tools, so it's fair to ask exactly how a platform handles accounting credentials once the connection goes live, not just at the moment of setup.
Pricing tends to track integration depth in a rough but consistent way. Entry-level tools start at a low monthly rate with basic calculations, mid-tier platforms run higher with multiple methodologies and more customization, and enterprise solutions can reach into the thousands annually. The number itself isn't the point. What matters is whether the tier an owner pays for actually delivers the integration sophistication that price implies.
The integration is where valuation quality starts, not where it ends. For business owners weighing these platforms as part of exit planning, that distinction carries real weight: clean financial data is the foundation an accurate valuation sits on, and an accurate valuation is what makes a buyer conversation credible instead of aspirational. What a platform does with the data it pulls, and what the owner or advisor does with what the platform produces, is what turns a number into something worth acting on.
Sources
- Best Business Valuation Software for Appraisers [2025 Guide]
- Business Valuation Software and Tools - Website Closers
- ValuAdder Business Valuation Software
- Capitaliz Features | All-Inclusive Business Valuation Software
- Best Business Valuation Software for Non-Financial Experts [2025] | Unbroker
- prnewswire.com